One platform for KYC, KYB and AML.Built to pass your sponsor bank's review.
AiPrise verifies individuals and businesses on one platform, in 200+ countries, with the fraud detection, audit trail and reporting your sponsor bank or BaaS partner expects. Convert more customers at account opening, let less fraud through, and consolidate the vendors.
Trusted by the neobanks building for the next billion customers
Built for the moments that cost aneobank customers
A neobank's compliance stack is judged three ways at once: by the customer who is trying to open an account, by the fraudster who is trying to open ten, and by the bank whose charter it runs on.

Half your applicants fail eKYC and you do not know why
Half your applicants fail eKYC and you do not know why
Thin-file customers, recent immigrants and anyone with a new address fail database matching that was built for someone else. Every failed match is an acquisition cost with nothing to show for it.
The SMB that will not send incorporation documents
The SMB that will not send incorporation documents
Freelancers, sole proprietors and small businesses abandon the moment you ask for paperwork. Verification has to come from the registry, not the applicant.
Your sponsor bank asks what fraud tools you have in place
Your sponsor bank asks what fraud tools you have in place
When the bank flags fraud on your accounts, the next question is about your stack. A cheaper vendor that stripped out fraud checks to hit a price point is not an answer you can give.
Five vendors, five contracts, five integrations
Five vendors, five contracts, five integrations
KYC from one provider, KYB from another, AML from a third, each with its own pricing tiers and minimums. The total cost is higher than any single invoice suggests.
Alert numbers you cannot trust
Alert numbers you cannot trust
False positives, common-name matches and gaps in alert generation mean the AML numbers do not hold up in an audit or a sponsor bank review.
A vendor the bank has not approved
A vendor the bank has not approved
The sponsor bank has to sign off on the risk scoring methodology before anything goes live. A vendor with no audit trail, no documentation and no references does not get through.
Who wework with
SMB and freelancer neobanks
Verifying the business and the owner in one flow
Consumer neobanks
Converting thin-file and first-time customers at account opening
Cross-border and diaspora banking
Onboarding customers whose documents come from somewhere else
Teen and family banking
Verifying guardians and account holders with age-appropriate checks
BaaS platforms
A compliance layer fintech clients and sponsor banks both accept
The compliance stack a neobank should have had from day one
One vendor for KYC, KYB and AML
Individuals and businesses, owners and entities, screening and monitoring, all on one platform and one contract. AiPrise covers 200+ countries with depth in the markets most vendors treat as an afterthought.
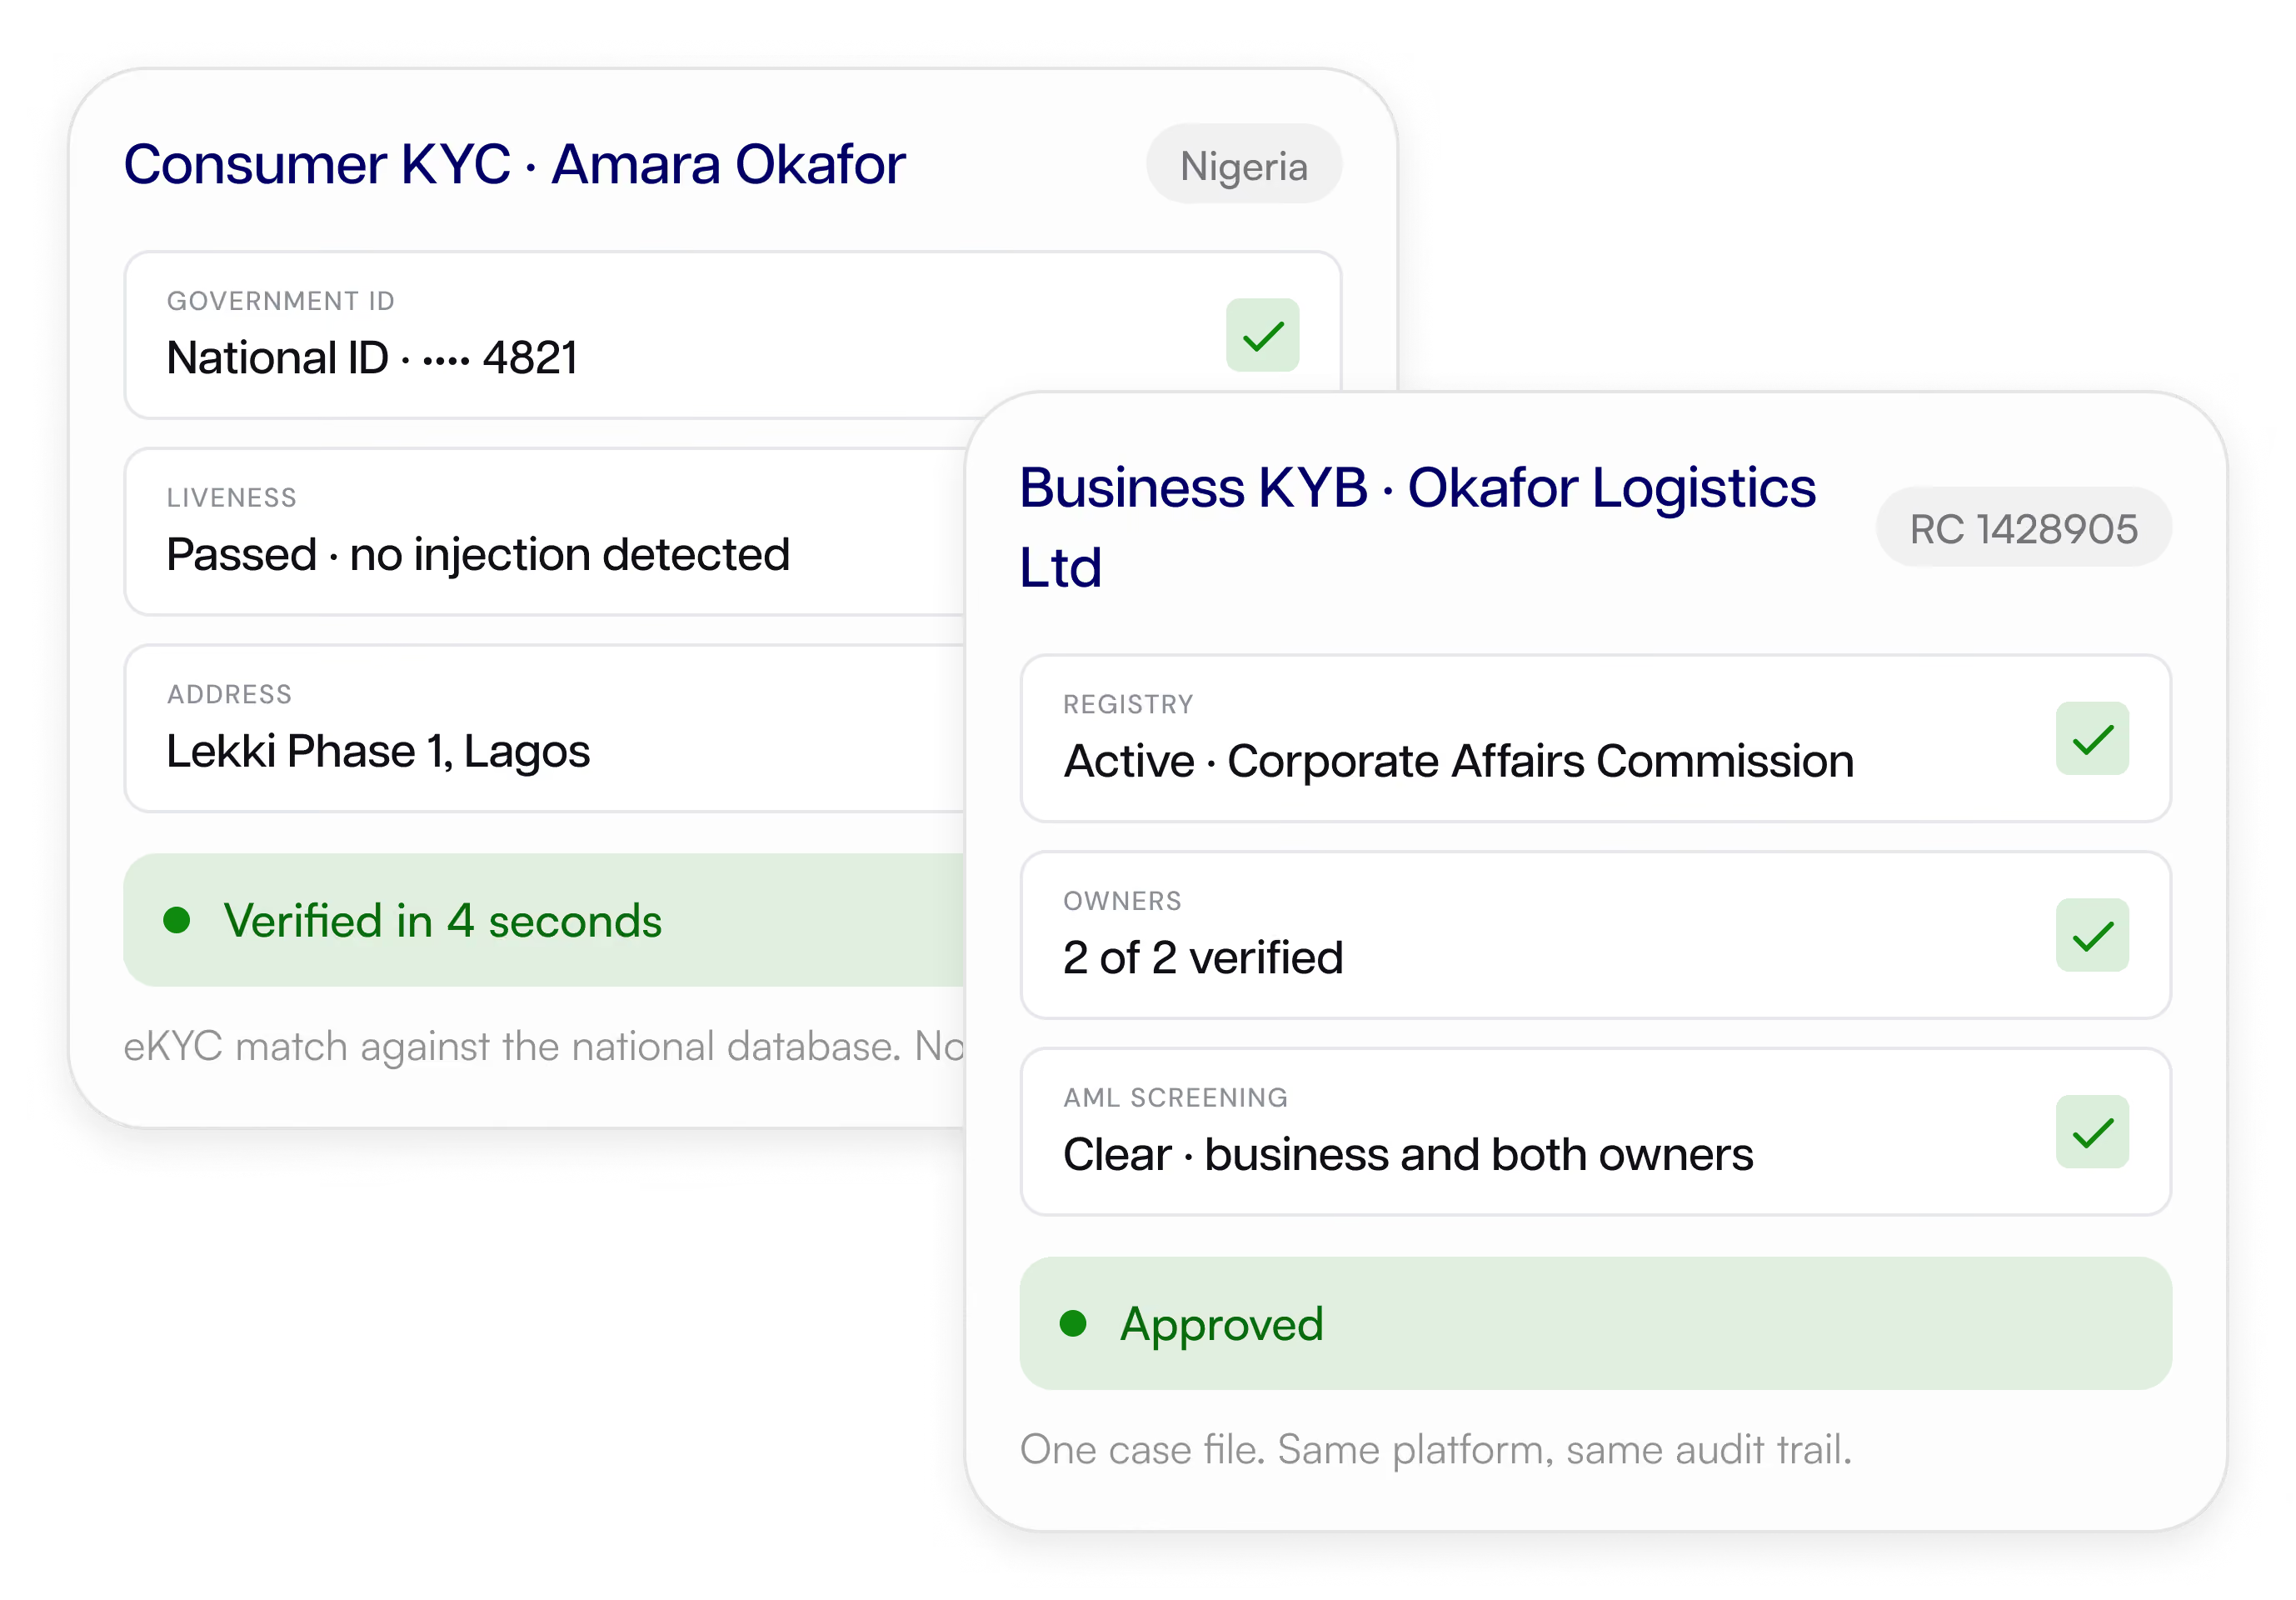
Consumer KYC: government ID, liveness, address and eKYC against official databases
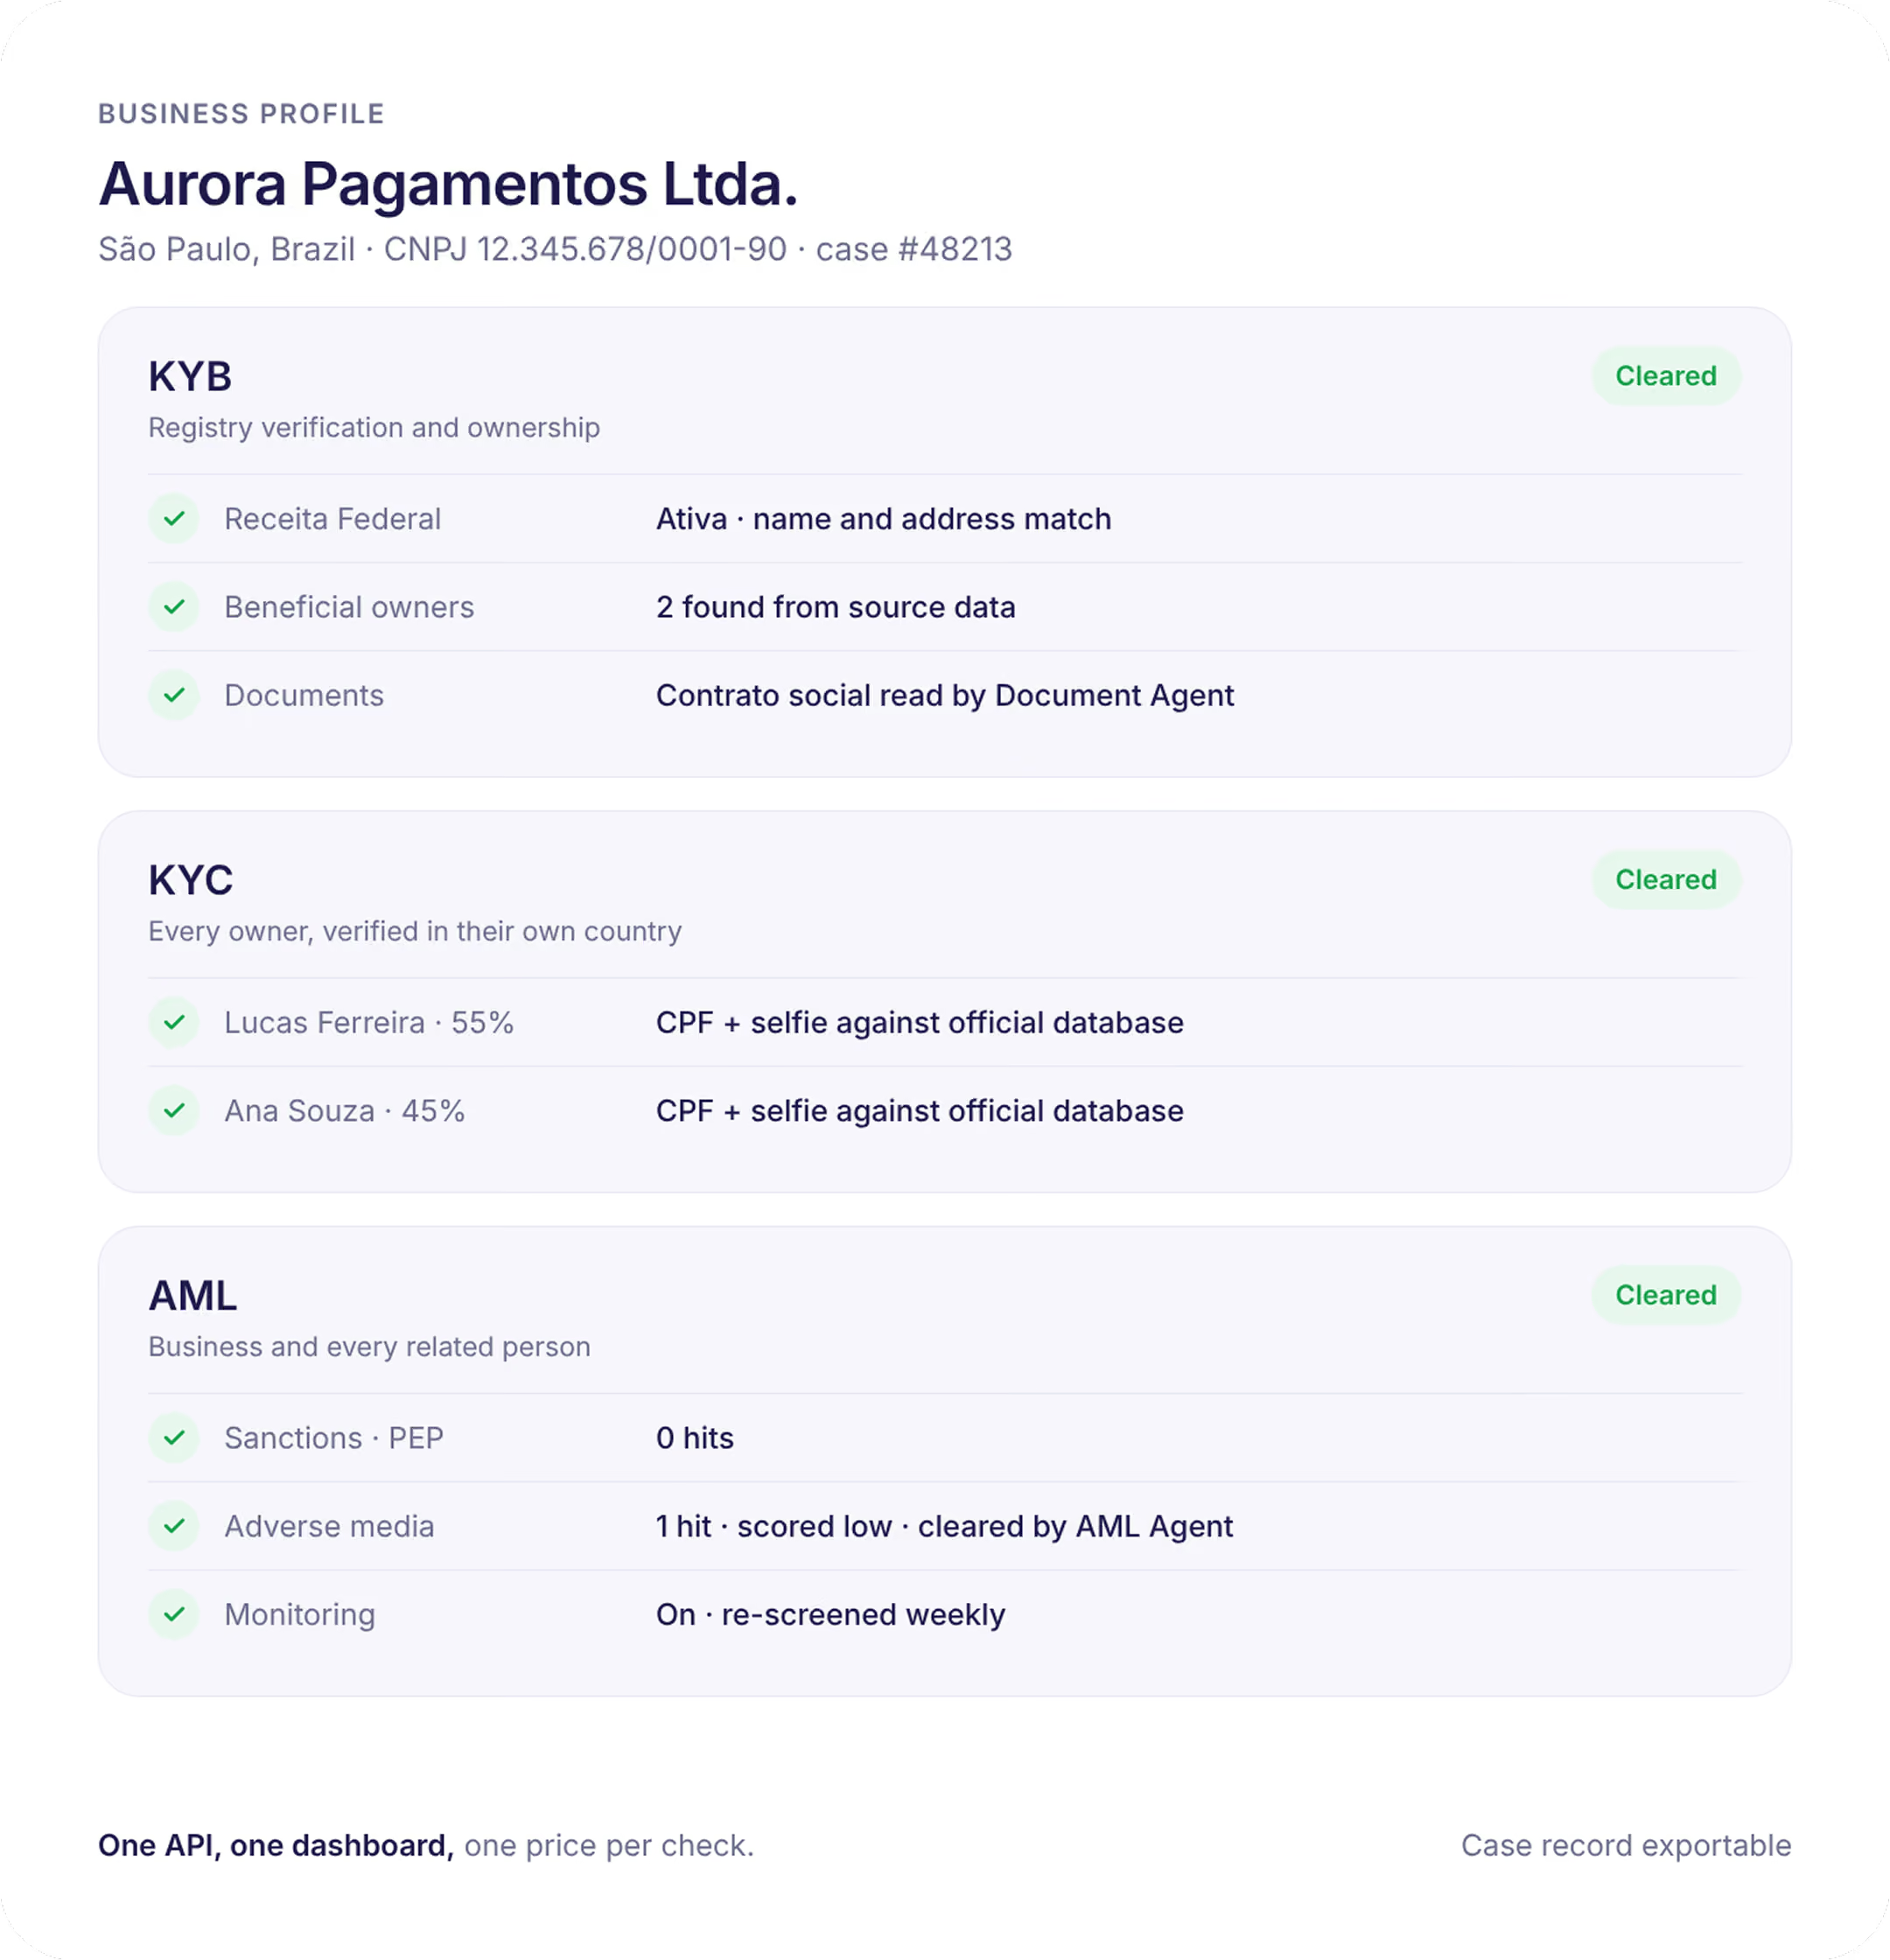
Business KYB: registry verification, UBO discovery and KYC on every owner
AML: sanctions, PEP and adverse media on individuals and businesses, with ongoing monitoring
One API, one dashboard, one all-inclusive price per check, no light and pro tiers

Convert more customers and let less fraud through
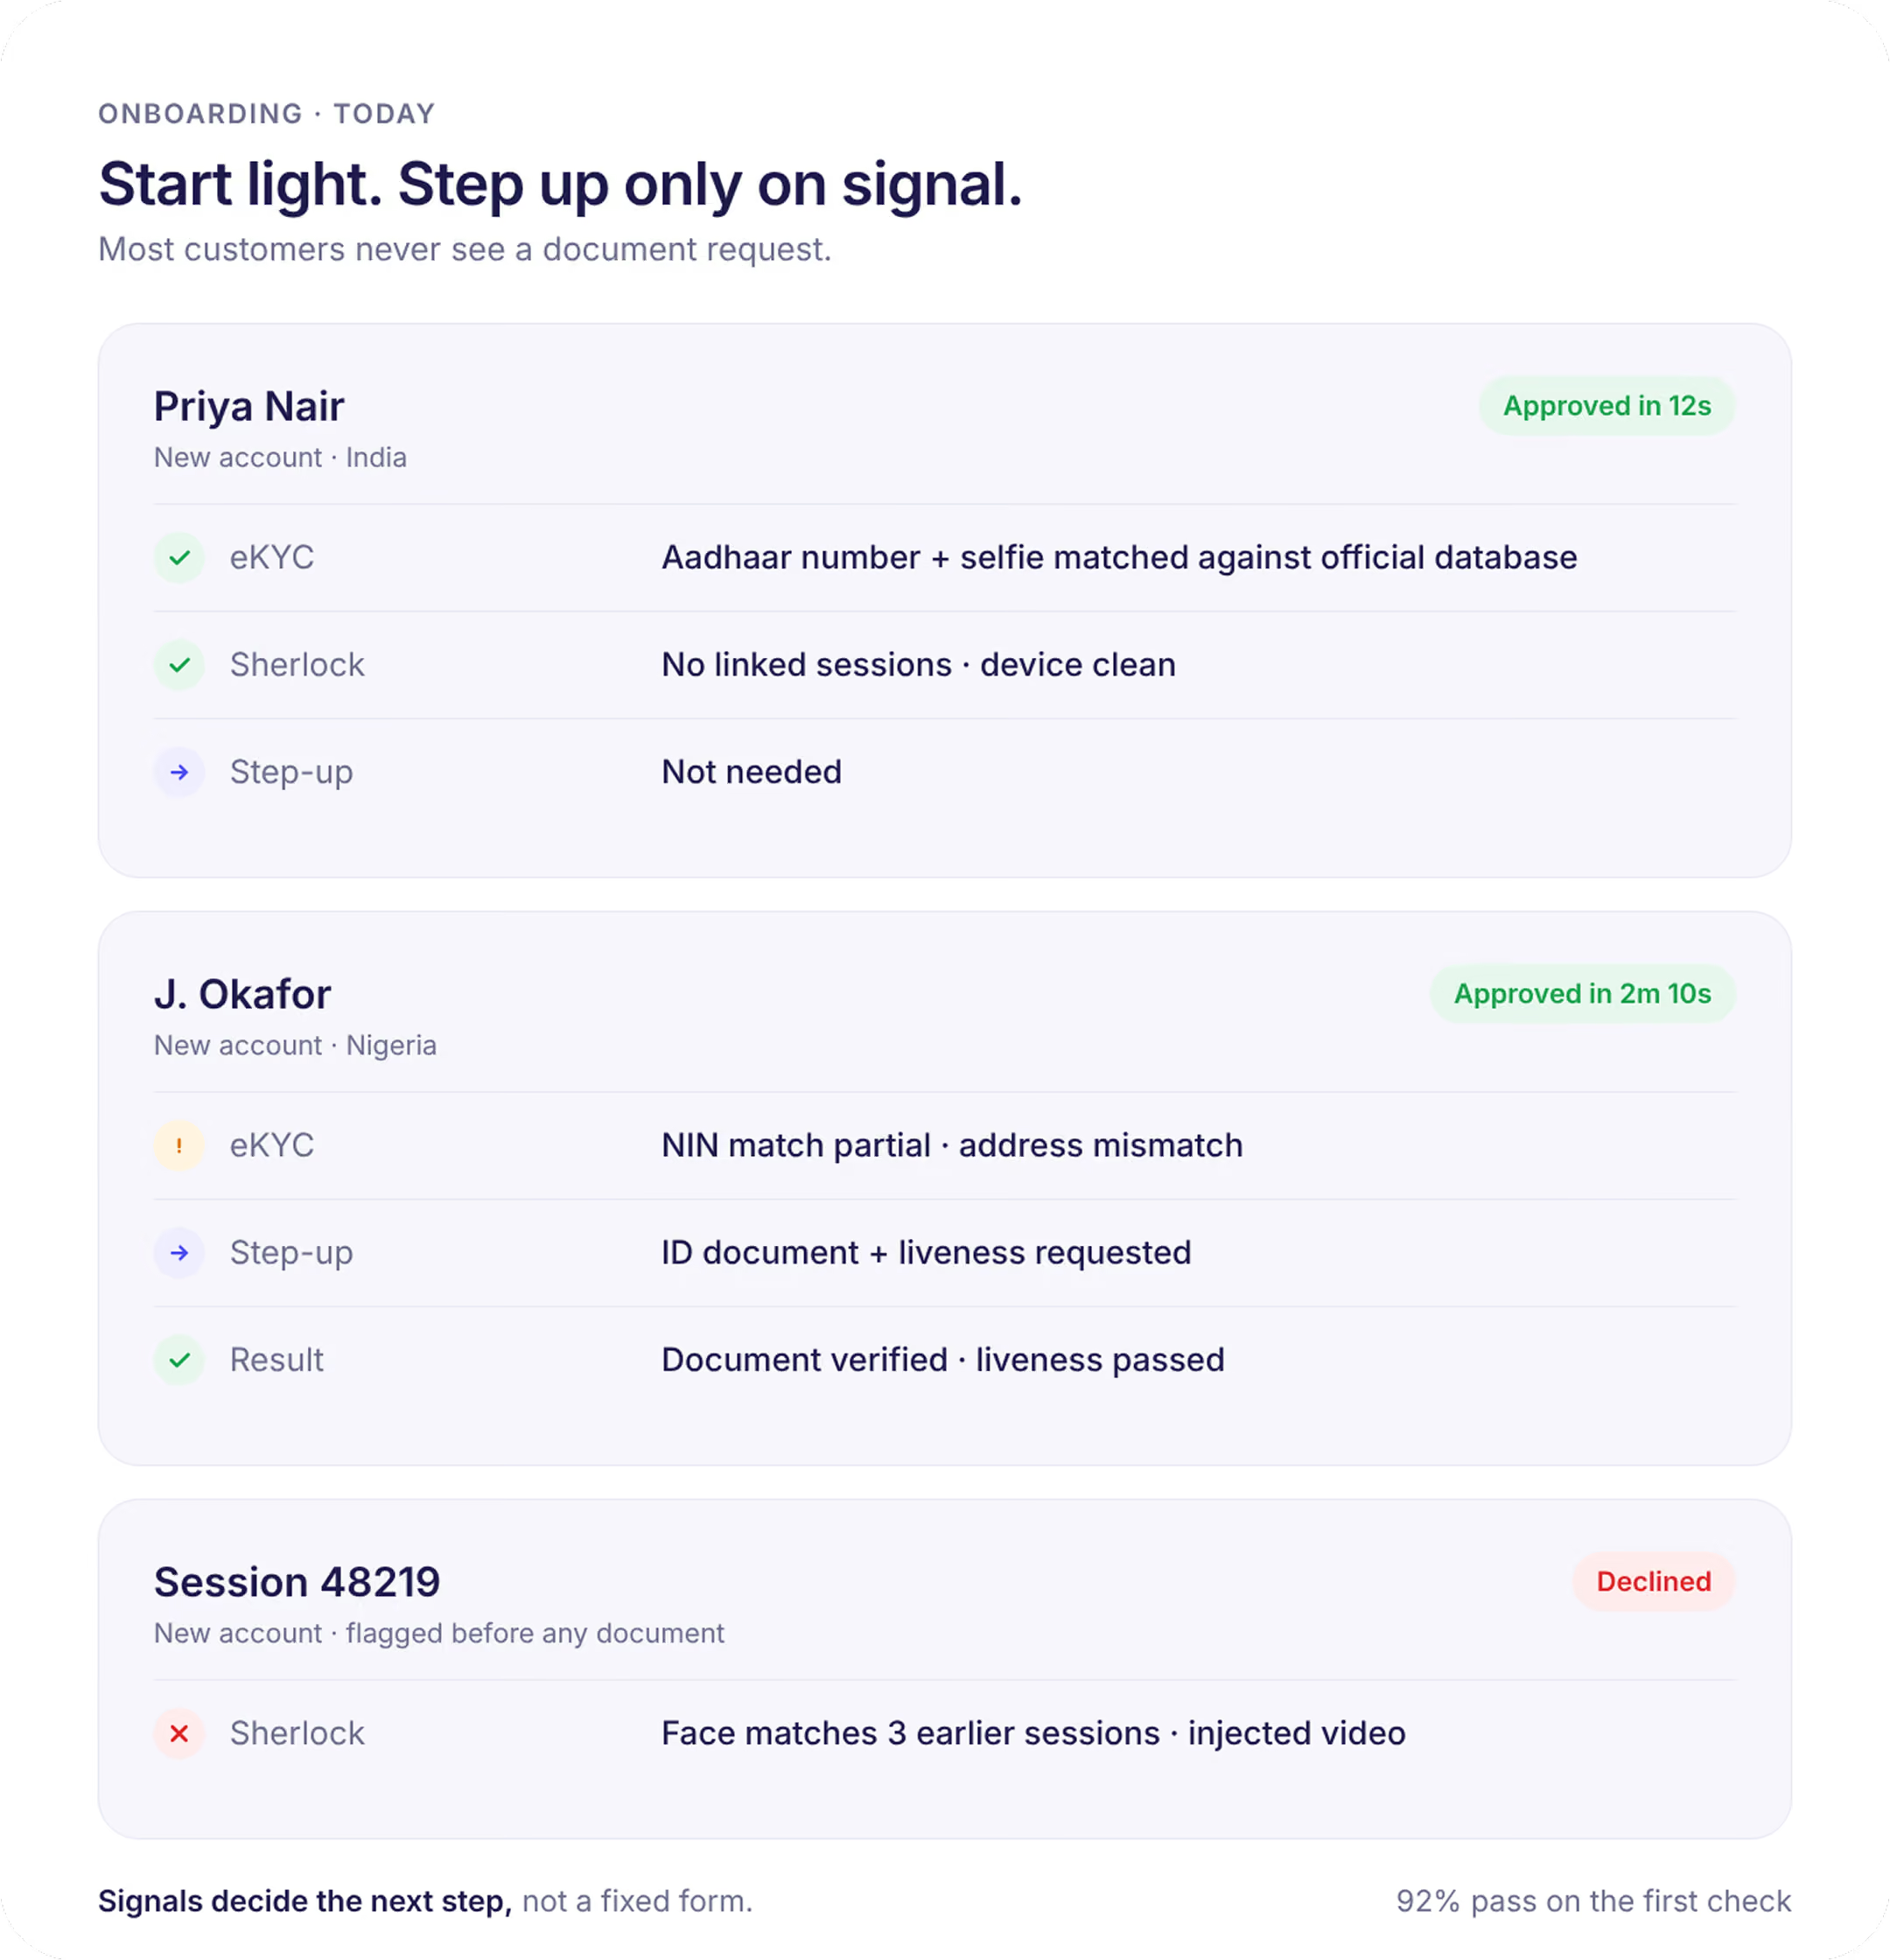
Conversion and fraud are the same problem seen from two sides. AiPrise starts with the lightest check that can pass a customer, steps up only when the signals say so, and runs fraud detection on every session.
eKYC first, with step-up to document and liveness verification only when needed
Business prefill from government registries, so SMBs are not asked for documents they do not have
Sherlock investigates KYC sessions for deepfakes and tampered IDs and links sessions sharing a face, ID number, device or network
Document Agent and Website Agent catch forged documents and synthetic businesses at signup
AI your sponsor bank will sign off on
Neobanks want AI, sponsor banks want evidence. AiPrise's agents give both: every decision comes with the reasoning and the source data behind it, in a format your BSA officer can defend and your bank can audit.
Athena Agent reviews the full business profile against registry, web and ownership data and returns a verdict with evidence
AML Agent scores every hit for relevance and writes a plain-language summary, so analysts clear false positives in seconds and the alert numbers hold up in an audit
Documented risk scoring methodology, exportable CIP and CDD reports, and a full audit trail on every case
Runs alongside a KYC or AML vendor your bank has already approved, and reference customers are available for your bank's due diligence

Monitoring that scales with your customer base, not your headcount
A neobank with a small compliance team and a large customer base cannot re-check everyone every day. AiPrise monitors for change and tells you when something moved.
Daily AML rescreening
Daily AML rescreening
Enrol once; a new report only when ownership, registration or status changes
Change-triggered monitoring
Change-triggered monitoring
AI-scored hits, configurable to the subset your policy requires
Scheduled re-verification
Scheduled re-verification
Individuals and businesses on the cadence your bank expects
Alerts where your team works
Alerts where your team works
Slack, email or webhook, with reliable counts for audits and bank reporting
Built for what your sponsor bank hasto show its regulator
A neobank inherits its sponsor bank's obligations, and the bank inherits the neobank's risk. The requirements land in the same place: identify every customer, know who owns every business, screen everyone, monitor for change, and keep a record the bank can hand to an examiner.
What the obligations ask for
Customer identification on every account holder (CIP)
Beneficial ownership and control persons on business accounts (CDD Rule)
Sanctions and PEP screening of customers and related persons (OFAC)
Ongoing customer due diligence
What AiPrise produces
Government ID, liveness and eKYC verification with source evidence
UBO and director discovery with identity verification on each person
AML Agent screening with scored, explained hits and cleared false positives
Change-triggered monitoring and daily rescreening with alerts
AiPrise is the verification and screening layer under your own BSA program. Transaction monitoring stays with your transaction monitoring provider, and AiPrise gives it a verified customer record to work from.